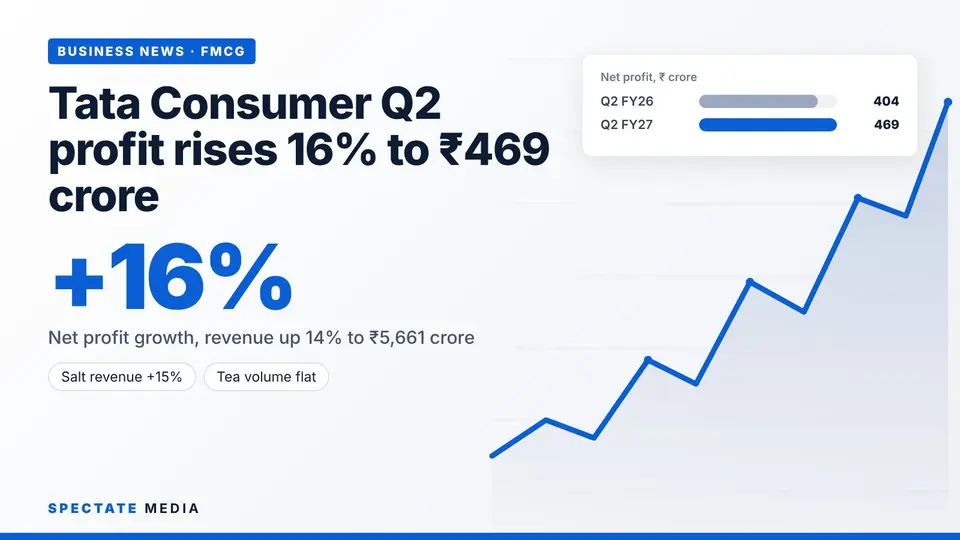
Tata Consumer Products reported net profit of ₹469 crore for the quarter ended 30 September 2026, up 16% from ₹404 crore a year earlier, according to Business Standard's report of 26 October. Revenue from operations rose 14% to ₹5,661 crore. Spectate Media has not seen the company's filing and relies on Business Standard and Upstox.
Where growth came from
India branded volumes grew 11%, led by salt, whose revenue rose 15%. Tea volumes were flat amid subdued category demand, and tea revenue dipped slightly. Growth businesses rose 40% and now make up 38% of the India business, with Tata Sampann revenue up 57% and ready-to-drink up 47%. International revenue rose 7% but fell 2% in constant currency. Tata Starbucks revenue grew 15% and the chain ended the quarter with 505 stores.
Margins, and a source conflict
Upstox puts EBITDA at ₹783 crore, up 16.5%, with the margin at 13.83%, up 31 basis points. Chief executive Sunil D'Souza cited 18% EBITDA growth, so the two figures differ. Business Standard gives no EBITDA margin.
Market reaction and views
The shares rose as much as 6.7% to ₹999.50 on NSE on 27 October and traded at ₹986 at 10:47 am, giving a market value of about ₹97,579 crore, per Upstox. Goldman Sachs expects pricing in India to accelerate in the second half, Jefferies said the quarter was ahead of expectations, and Citi estimates a 50 basis point EBITDA margin gain in the second half. These are brokerage views, not outcomes.
Key numbers
- Net profit: ₹469 crore (+16% from ₹404 crore)
- Revenue from operations: ₹5,661 crore (+14% year on year)
- India branded volume: +11% (Led by salt; tea flat)
- Share high, 27 October: ₹999.50 (Up as much as 6.7%)
What boards and CFOs should note
Three points. First, volume growth came from salt and newer categories, while tea, the core, was flat. Second, margin recovery depends on price increases that brokerages say have not fully flowed through. Third, the EBITDA growth figure depends on which source is used. Not investment advice.
Source: Business Standard, 26 October 2026. This is a summary of a news report, published as general information. It is not legal, tax or investment advice.
This article is journalism and commentary. It is not a recommendation to buy or sell any security, and it is not professional advice. Read the full disclaimer.