The Ministry of Finance said on 17 October 2026 that no legal bar prevents the Government from reducing or divesting its stake in IDBI Bank, according to a Corplawupdates report on a Press Information Bureau release (ID 2324612). Spectate Media has not checked the original release.
The reasoning
The ministry says that in 2003, during the debate on the IDBI (Repeal) Act, an amendment to restrict dilution was moved but rejected, so it never became law. The Act converted IDBI into a company under the Companies Act. The ministry also cites two budget speeches: 2016-17 (paragraph 93), which spoke of reducing the stake to below 50%, and 2021-22 (paragraph 84), which listed IDBI Bank among strategic disinvestment transactions.
The 2018 ruling
It relies on the Delhi High Court judgment of 17 December 2018 in All India IDBI Officers' Association v. Union of India. The court dismissed the association's petition against dilution. It held that statements in Parliament cannot override an enacted statute and that promissory estoppel did not apply. At paragraph 42, it found "no ambiguity" in the 2003 Act and no basis to read in a bar on reducing the Government's stake.
The sale
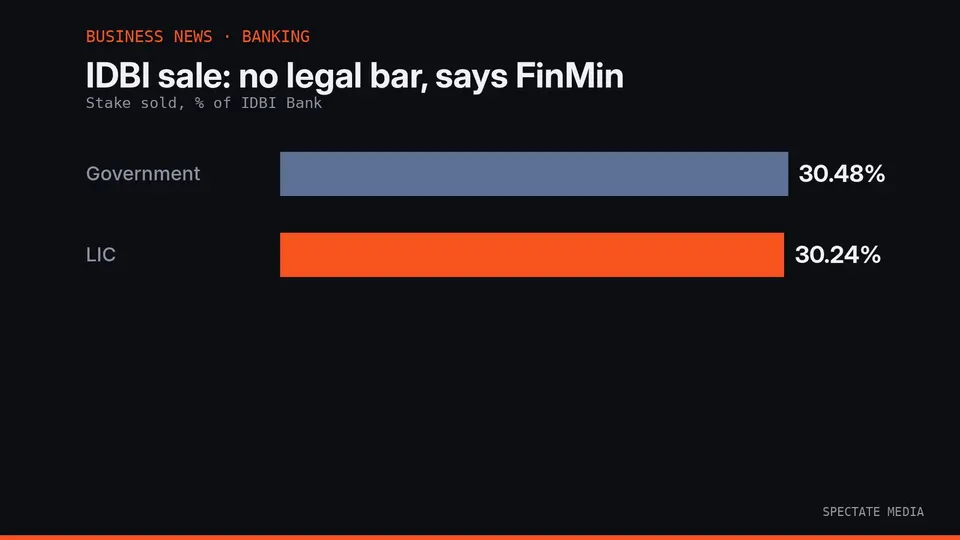
Per the report, the Cabinet Committee on Economic Affairs approved on 14 October the sale of a 60.72% stake to Fairfax Financial Holdings' Canadian entity at ₹81 a share, about ₹52,878 crore, which is within ₹1 crore of the ₹52,877 crore in earlier reports. The Government sells 30.48% and LIC 30.24%; the Government would keep 15% and LIC 19%.
What the statement does not change
The release addresses legal authority only. It does not change the deal's commercial terms, regulatory approvals or employment matters.
Key numbers
- Stake sold: 60.72% (To Fairfax's Canadian entity)
- Sale price: ₹81 a share (About ₹52,878 crore)
- Government sells: 30.48% (Keeps 15%)
- LIC sells: 30.24% (Keeps 19%)
What boards and CFOs should note
Three points stand out. First, the ministry is answering a legal objection in public, which suggests the challenge was expected. Second, the argument rests on the 2018 judgment and the text of the 2003 Act. Third, approvals still outstanding are separate from this statement.
Source: Corplawupdates, 17 October 2026. This is a summary of a news report, published as general information. It is not legal, tax or investment advice.
This article is journalism and commentary. It is not a recommendation to buy or sell any security, and it is not professional advice. Read the full disclaimer.